Since the parents of the Baby Boomers lived through the economic hardships that followed the Great Depression, that generation grew up with financial advice centered on being careful with money, given the economic uncertainty of the times. While some of these Boomer money rules might seem outdated today, others remain effective. Drawing on information from the Consumer Financial Protection Bureau, the FDIC, and other sources, we’ll reveal the Boomer rules that still make sense to follow nowadays!
Pay Yourself First, Even If It’s Only a Few Dollars
One of the Boomer money rules that remains effective today is to set aside money for savings as soon as you receive your income, rather than waiting until the end of the month. By putting that money, even a small amount, into a separate account, you can build a habit and create a financial cushion for unexpected expenses, according to the CFPB.
Never Go Grocery Shopping Without a List
Checking your pantry, planning your meals, and writing down what you need to buy before heading to the supermarket will help you reduce your purchases. Following these Boomer money rules, including organizing your meals for the week, will help you know exactly which ingredients you need and avoid being swayed by promotions for non-essential food items. According to the FDIC, you should build a weekly menu based on the groceries you already have in your freezer and pantry to save money.
Don’t Buy Something Just Because It’s on Sale
Another of the Boomer money rule is that a bargain isn’t really one if you are buying an item you don’t actually need or hadn’t planned to purchase. Even if you buy an unnecessary item at a 30% or 50% discount, you are still increasing your total spending. The FDIC specifically cautions that a sale or coupon item can still be more expensive than a comparable alternative.
Keep an Emergency Fund for Things That Break
An old-school Boomer money rule is to keep some money saved for potential car repairs, medical expenses, appliance failures, and other unexpected issues that might arise. Baby Boomer believed that an ordinary household emergency can turn into costly credit card debt if you don’t have the cash reserve. An emergency fund is intended for unplanned needs, not predictable expenses like holiday gifts.
Use Something Up Before Replacing It
Finishing the products you already have at home before buying new ones is another of the Boomer money rules that still makes sense today. If you purchase a replacement before using up the current item, you end up creating household clutter and unnecessary spending. Furthermore, this can be risky when stocking up on perishable food, as there is a chance the items might expire, according to the EPA.
Trending on Cheapism


Take Care of What You Own
Performing regular maintenance on your household appliances, such as dishwashers, washing machines, and other expensive items, is generally more cost-effective than having to replace them due to a complete breakdown. These Boomer money rules also apply to everyday maintenance: cleaning appliance filters, checking fluid levels in a vehicle, and following product instructions can help prevent repairs or premature replacement.
Set Money Aside for Expenses You Know Are Coming
As the Christmas season approaches, or when you have to pay for school expenses, property taxes, or other predictable bills, it is best to spread the cost over the months, since these are expenses you know will arise. This is another of the Boomer money rules that can help you avoid financial surprises. By distributing the cost throughout the year, you reduce the temptation to charge it to a credit card. Dividing the total by 12 months allows you to know exactly how much money to set aside each month, according to the CFPB.
Pay Bills On Time To Avoid Throwing Money Away
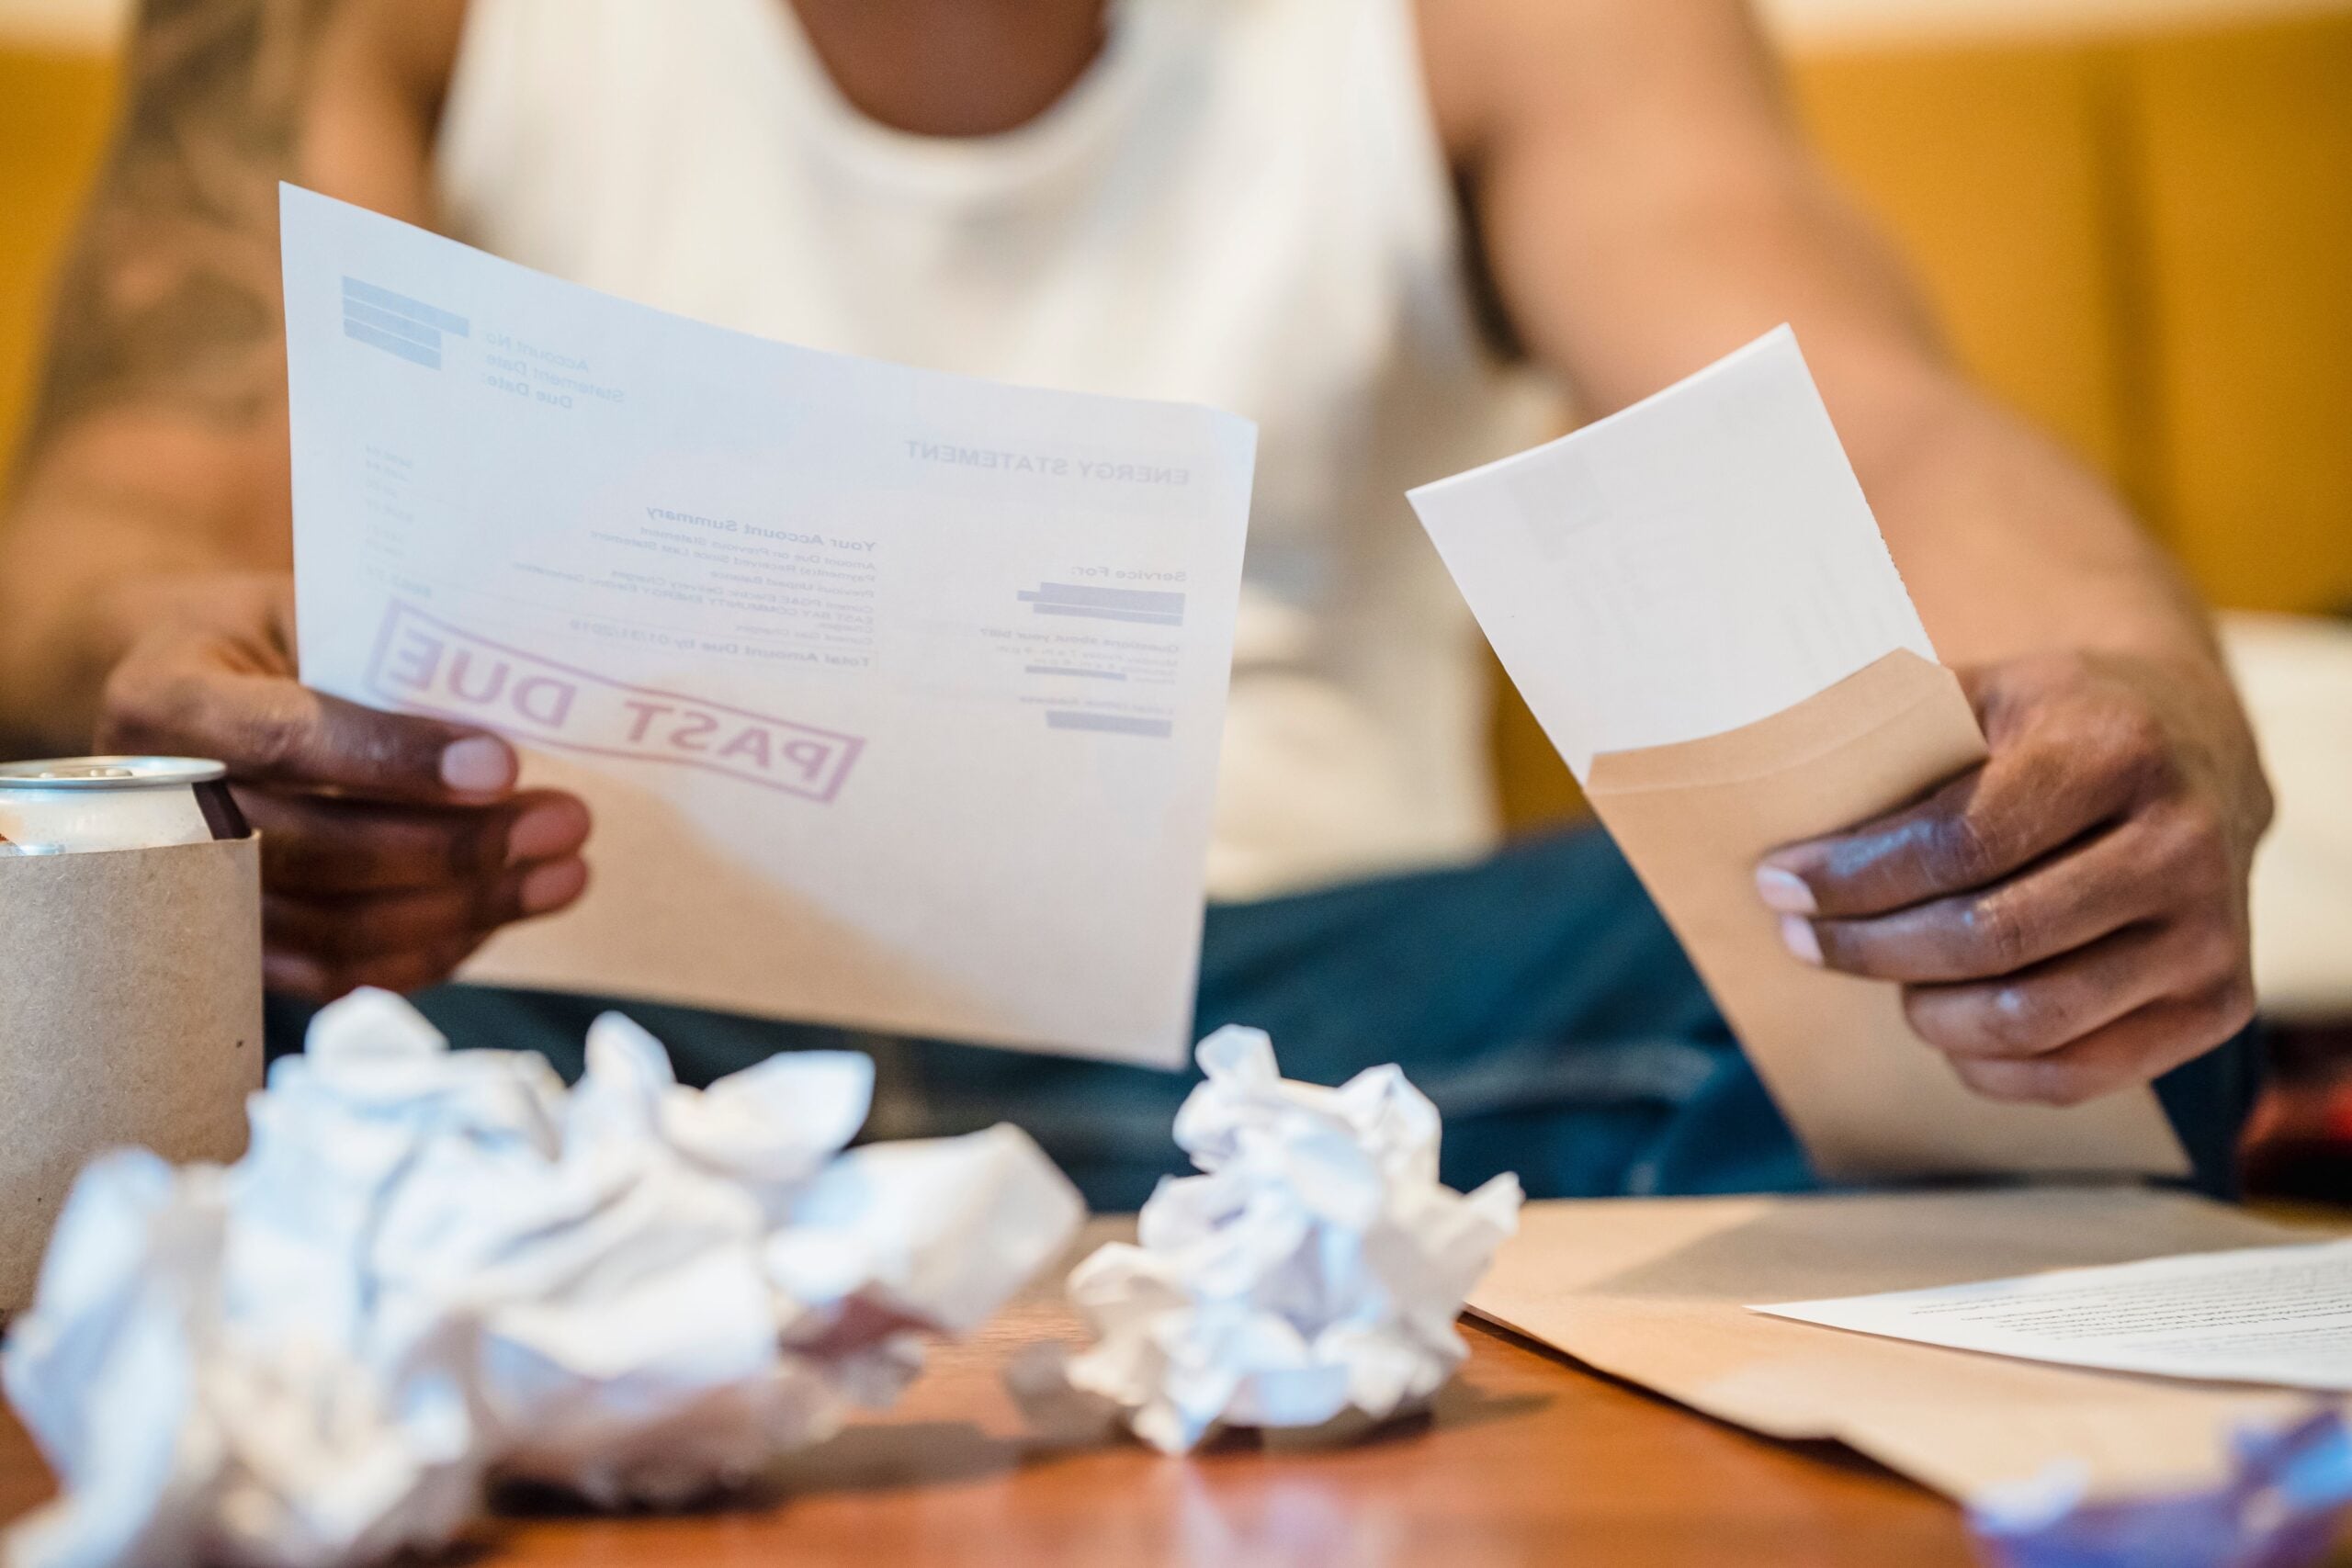
Missing a bill payment deadline will result in additional costs due to interest. Late charges, service interruptions, and potential negative impacts on your credit score can be far more serious than simply paying the original bill on time, according to FDIC. One of the Boomer money rules worth keeping is to use a calendar to keep track payment due dates or set up automatic payments.
Sign up for our newsletter
Don’t Borrow Money for Every Want
Be careful when the urge to shop strikes. If it isn’t an essential purchase, it can wait. A smart way to handle this is to look at the total repayment amount and verify what you will be paying in monthly installments before accepting any financing. These Boomer money rules also apply when borrowing money from someone: you should consider how you plan to fund the repayment.
Make Leftovers Part of the Meal Plan
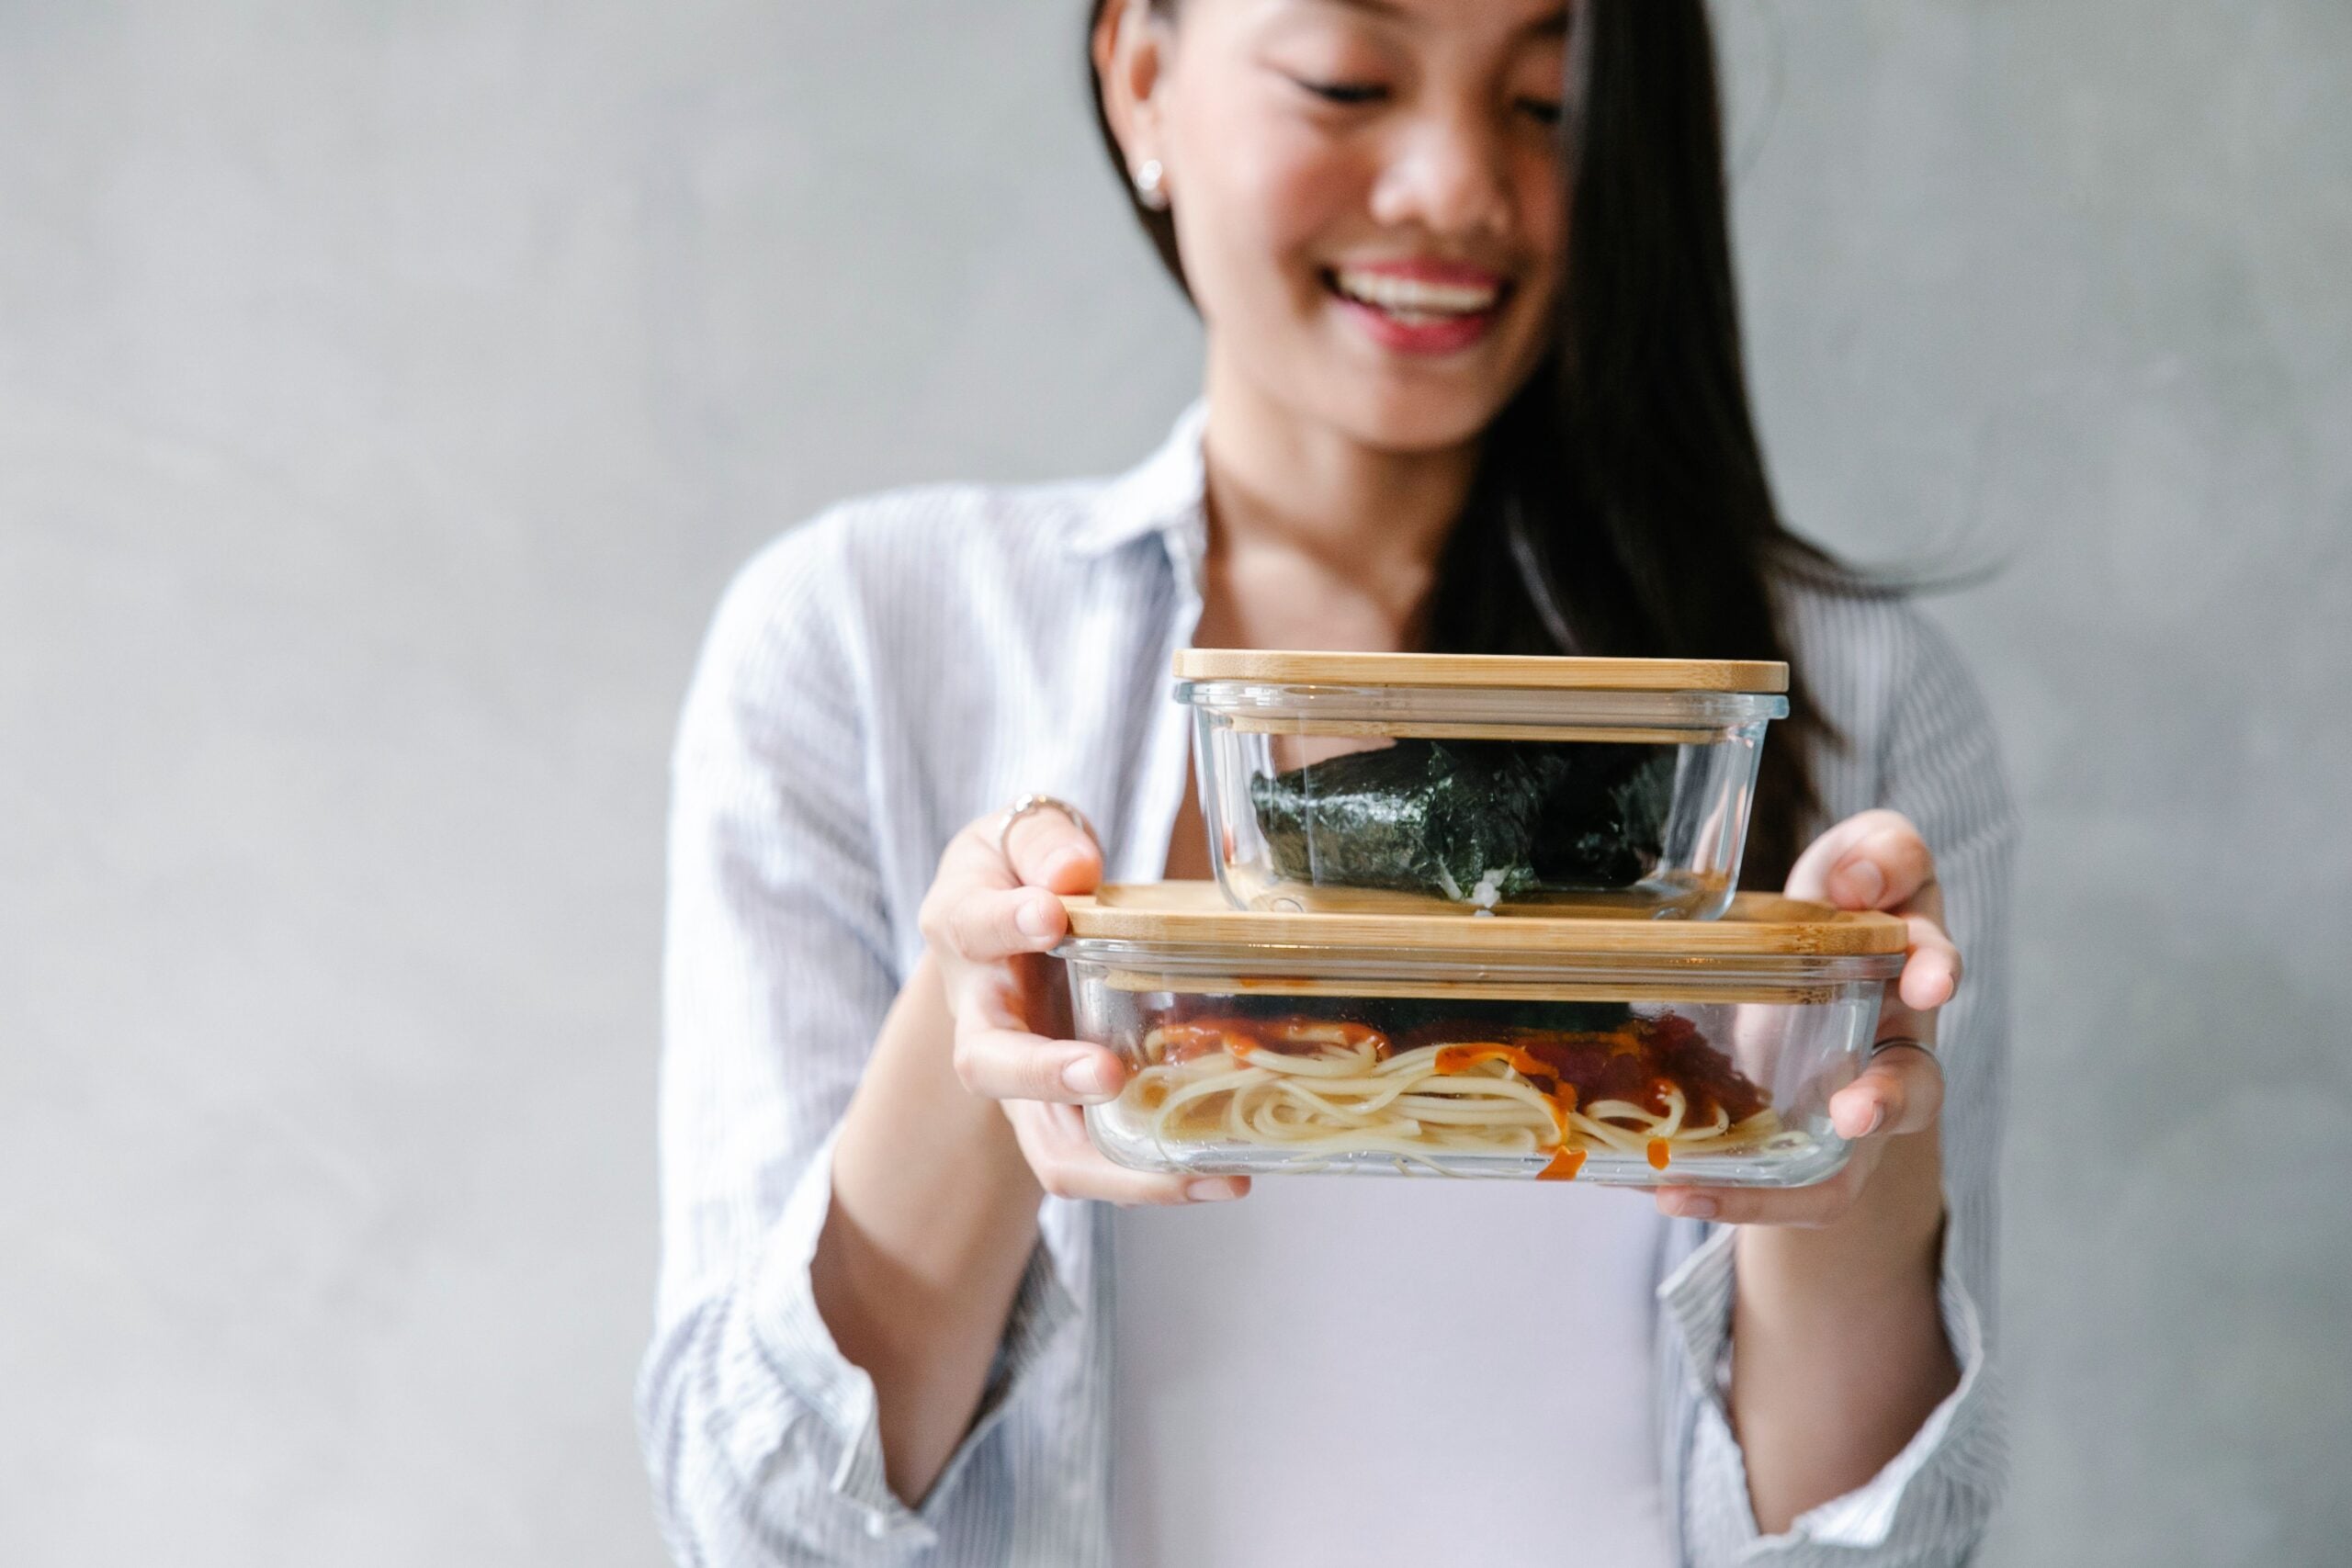
In addition to maintaining a weekly food plan to ensure you buy the right ingredients at the grocery store, keep in mind that you may end up with leftovers. For instance, today’s roast chicken, vegetables or rice could be repurposed into a casserole, soup, or a lunch dish later in the week. Most cooked leftovers should be refrigerated promptly and consumed within 3 to 4 days. One of these practical Boomer money rules will help you limit food waste and unnecessary grocery shopping trips.
Compare the Cost, Not Just the Monthly Payment
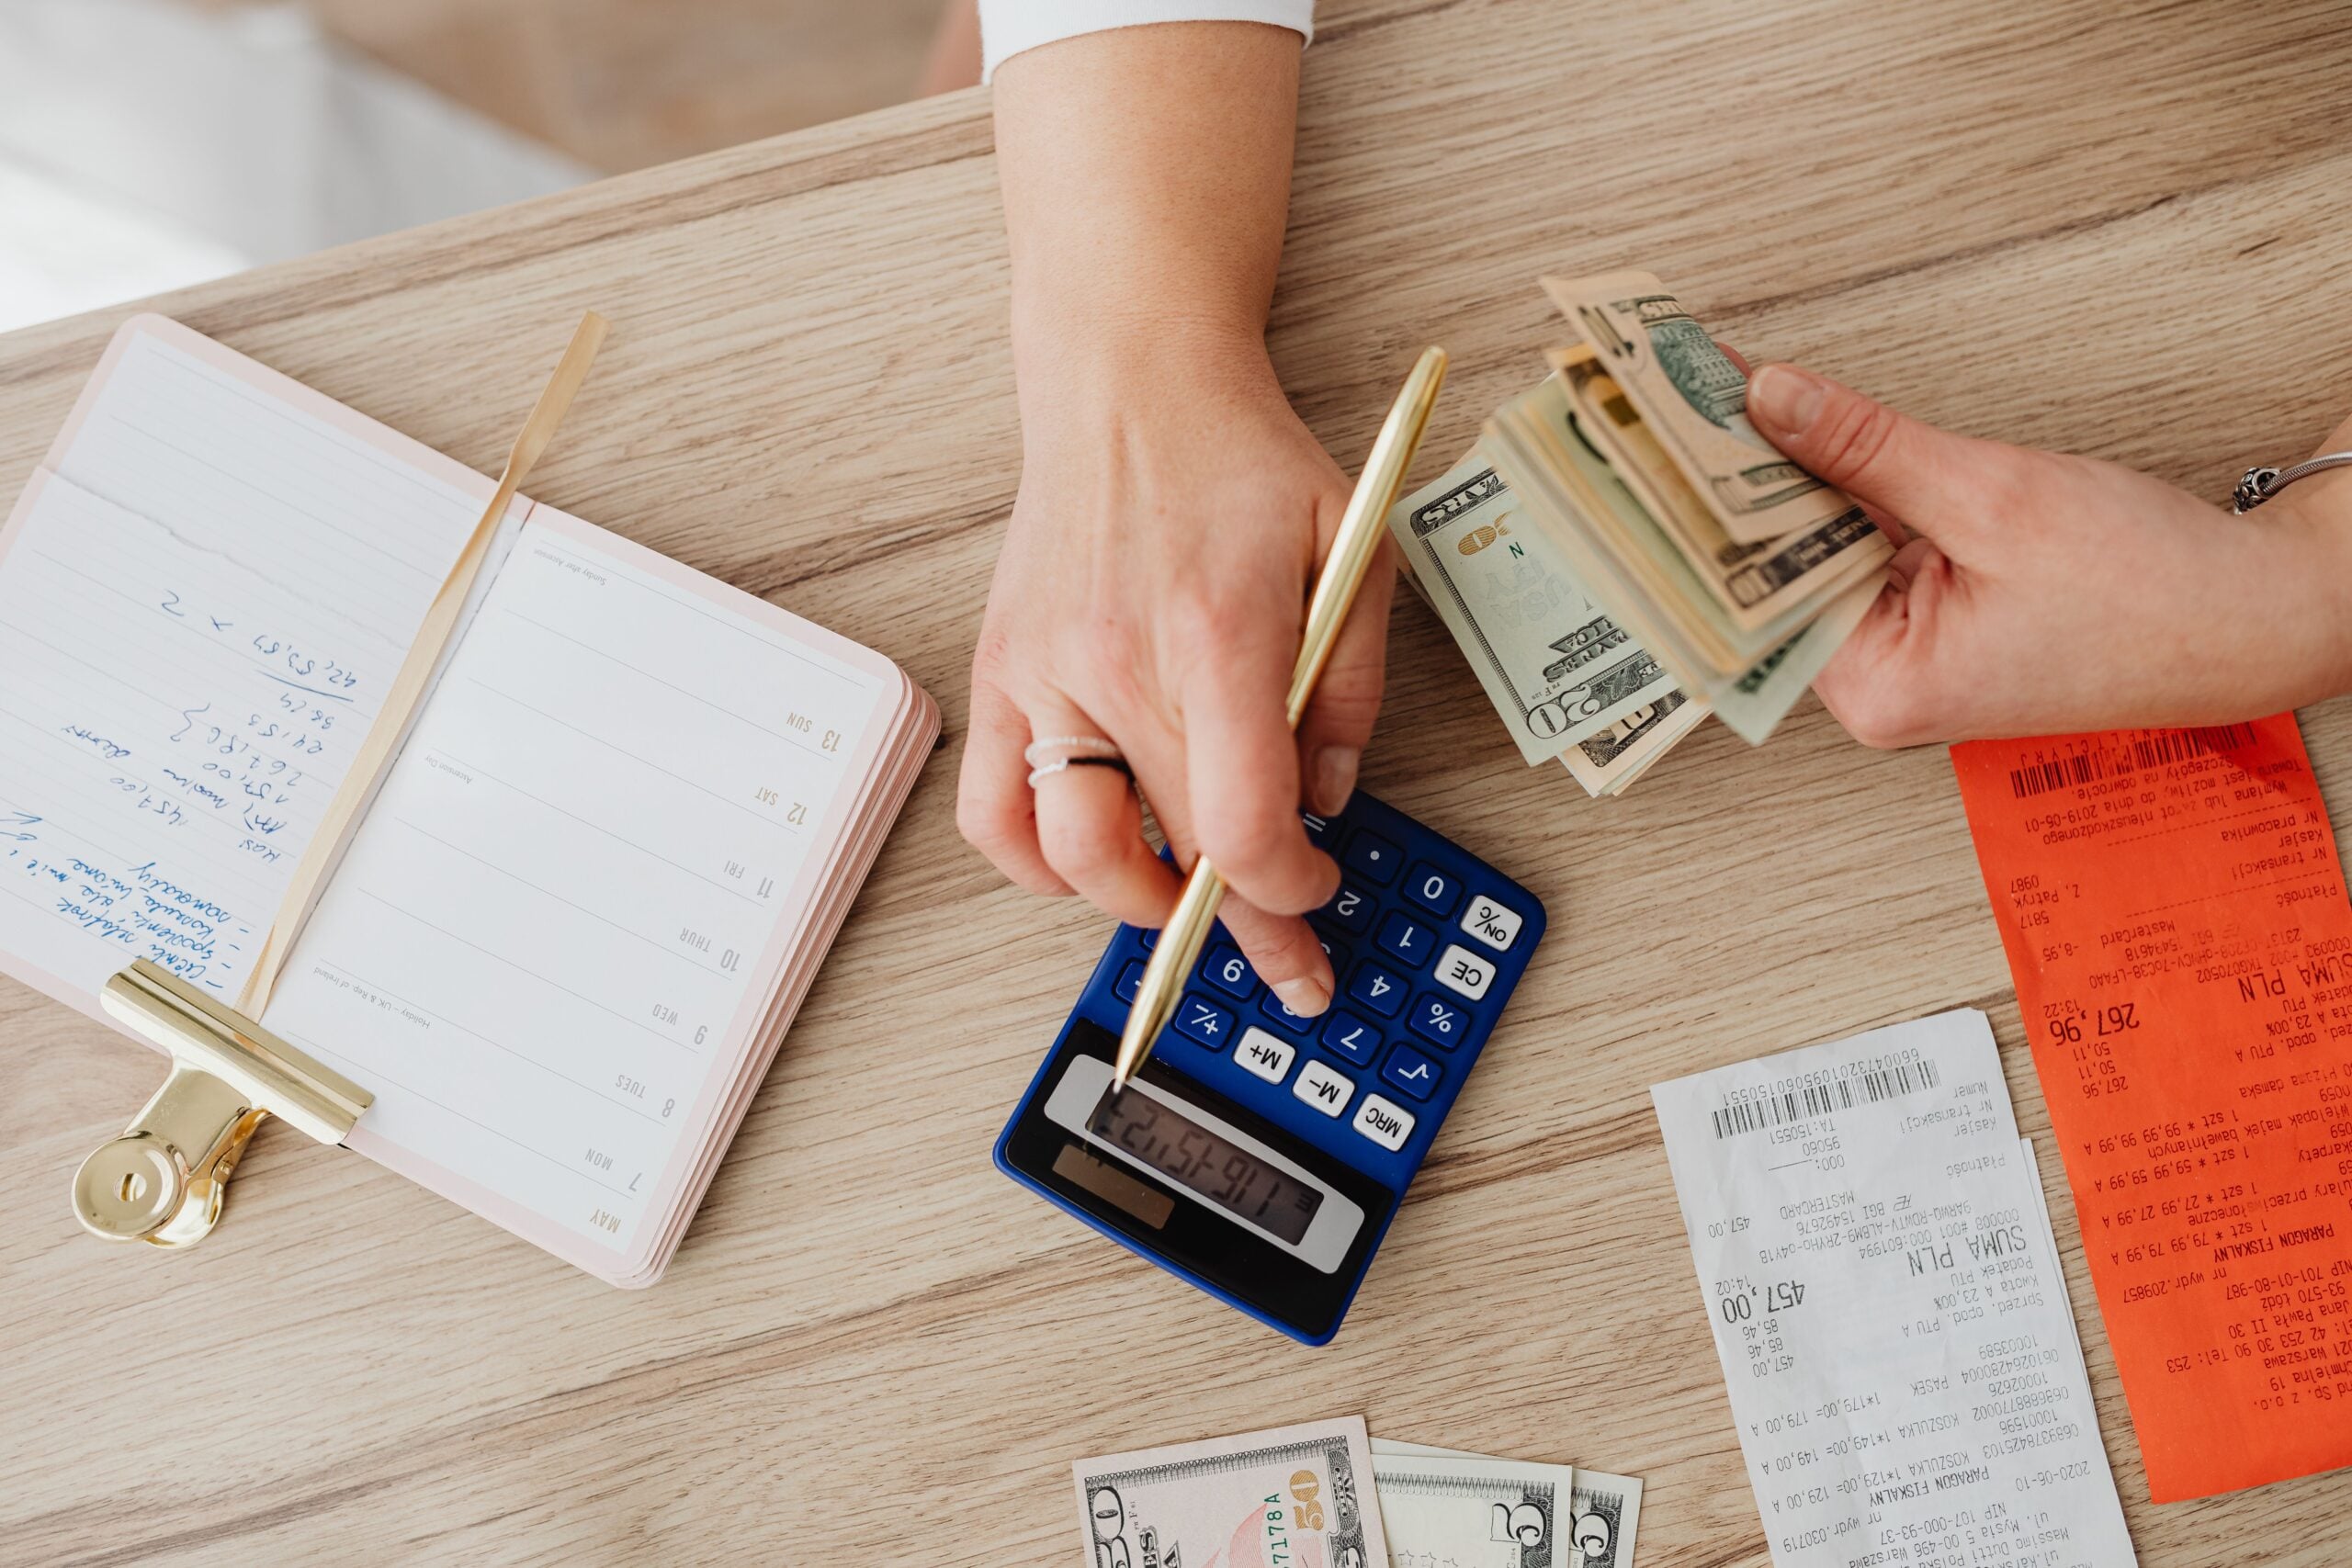
Even when you decide to make a purchase using monthly payments, pay attention to the full price before making a decision. What appears to be a small monthly payment may conceal longer loan terms, higher interest charges, or costly extras. A purchase that offers a lower monthly payment is not necessarily a better deal if the repayment period is extended significantly. This is one of the Boomer money rules that remain useful today, according to the CFPB.
Keep Saving After a Debt Is Paid Off
Once a loan or recurring payment ends, the best way to save money is to maintain the habit of setting aside a certain amount, rather than simply spending the full amount you were previously paying. Redirecting a past payment toward savings is one of the Boomer money rules that can be very useful for handling emergencies, covering vehicle repairs, or building up your retirement savings account, according to FDIC.
Conclusion
Among the Boomer money rules that remain applicable today are practices such as planning, avoiding unnecessary expenses, and making use of the resources you already have. While modern tools can simplify automated savings, you must still cultivate the habit of setting that money aside. Ultimately, the goal is not to replicate every financial decision made by a previous generation, but rather to apply the principles that remain useful in today’s economy.