Retirement can change the way you think about a dollar. When more of your income comes from Social Security, pensions, or savings rather than a paycheck, senior discounts for retirees can make recurring expenses a little easier to manage.
That doesn’t mean retirement needs to become an endless hunt for coupons. In many cases, saving money is simply a matter of knowing which expenses routinely come with senior discounts, government assistance, membership perks, off-peak rates, or even free alternatives. AARP’s 2026 savings guide points to opportunities across everything from groceries and travel to entertainment, utilities, insurance, and health care.
Of course, “senior” can mean 55 at one business and 65 at another, and plenty of discounts depend on location, income, insurance coverage, or membership. But before automatically paying the price you’re quoted, these are 12 expenses worth giving a second look.
National Park Admission
If retirement has finally given you time for that national park road trip, don’t keep paying individual entrance fees without checking whether you qualify for a Senior Pass. U.S. citizens and permanent residents age 62 and older can purchase an annual Senior Pass for $20 or a lifetime version for $80. The passes cover entrance or standard amenity fees at participating federal recreation sites.
For anyone who plans to visit several fee-charging parks over the next few years, the lifetime option can be particularly hard to beat. The pass can also provide discounts on certain amenity fees, including some camping charges, though it doesn’t cover everything.
Groceries on the Wrong Day
You don’t necessarily need to change supermarkets to cut your grocery bill. You may just need to change the day you shop. AARP’s 2026 roundup found that a number of grocery chains offer older shoppers discounts of roughly 5% to 10% on designated days, including participating Albertsons, Harris Teeter, and Weis Markets locations.
The catch is that these deals are far from standardized. The minimum age, eligible products, participating locations, and loyalty-card requirements can all differ. Before reorganizing your grocery routine, ask your regular store what it offers. If you can knock even 5% off a bill you’re paying every week anyway, the savings can become meaningful over a full year.
Prescription Drugs
A high price at the pharmacy counter shouldn’t automatically be the end of the conversation. Retirees with Medicare drug coverage may have several ways to bring prescription costs down, from using a plan’s preferred pharmacy to asking about generics and formulary alternatives.
For lower-income beneficiaries, Medicare’s Extra Help program can reduce Part D costs. In 2026, the income limit is $23,940 for an individual and $32,460 for a married couple, with separate resource limits. Medicare Part D also has a $2,100 annual out-of-pocket cap for covered drugs in 2026.
That doesn’t mean switching or skipping a medication because it’s expensive. Instead, ask the pharmacist, insurer, and prescriber whether there is a less expensive way to get the treatment you need.
Medicare Premiums and Cost Sharing
Medicare comes with plenty of costs of its own, but some retirees may qualify for help paying them. Medicare Savings Programs can cover certain premiums and, depending on the program, deductibles, coinsurance, and copayments.
For example, the Qualified Medicare Beneficiary program has a 2026 federal monthly income limit of $1,350 and a resource limit of $9,950 for an individual. The limits are higher for married couples, and Medicare notes that some states have more generous eligibility rules.
For someone who qualifies, the savings could dwarf the money saved through ordinary senior discounts. It’s worth checking eligibility rather than assuming every Medicare-related bill is simply a fixed cost of getting older.
Gym Memberships
Before signing another annual gym contract, take a look at your health insurance benefits. Original Medicare doesn’t cover standard gym memberships or fitness programs, but some Medicare Advantage plans, other Medicare health plans, and Medigap policies may offer fitness benefits.
Coverage varies widely, including which facilities and programs qualify, so don’t assume your favorite gym is included. But a quick call to your insurer could reveal that you’re already paying for access to a fitness program through your health coverage — making a second membership unnecessary.
Trending on Cheapism
Tax Preparation
A straightforward tax return doesn’t necessarily require handing over a few hundred dollars to a commercial preparer. The IRS Tax Counseling for the Elderly program provides free tax help to people age 60 and older, with particular attention to issues that affect older taxpayers, including pensions and retirement.
The program isn’t some tiny side project, either. The IRS announced $53 million in grants for the TCE and Volunteer Income Tax Assistance programs in 2026 to support free federal tax-return preparation.
More complicated situations involving businesses, estates, unusual investments, or specialized tax planning may still justify paying an expert. But retirees with relatively uncomplicated returns should see what’s available for free before opening their wallets.
Hotels
Retirement can come with one major travel advantage: flexibility. If you don’t have to plan every vacation around weekends, school calendars, or limited PTO, there’s little reason to automatically accept the first hotel rate you see.
Check the hotel’s standard rate against any senior or AARP rate, AAA discount, loyalty-member price, and off-peak dates you can use. Older travelers are already embracing this approach: AARP found that 89% of adults 50 and older shop for bargains at least sometimes when planning trips, while many use loyalty programs and rewards to lower costs.
Just make sure you’re comparing the final bill. A cheaper room can stop looking like a bargain once resort fees, parking charges, and restrictive cancellation policies enter the picture.
Rental Cars
The price of a rental car can seem almost arbitrary. Rates can change depending on where you book, when you reserve, demand at the destination, and which memberships or discount codes you qualify to use.
AARP members, for example, have access to negotiated discounts with several rental companies, including potential savings at Avis and Budget. AAA memberships, credit-card benefits, loyalty programs, and other affiliations may produce different rates, so don’t assume any single “discount” is automatically the best deal.
And if your reservation can be canceled without a penalty, check the price again before the trip. You may be able to rebook the same car for less if rates have dropped.
Sign up for our newsletter
Train Tickets
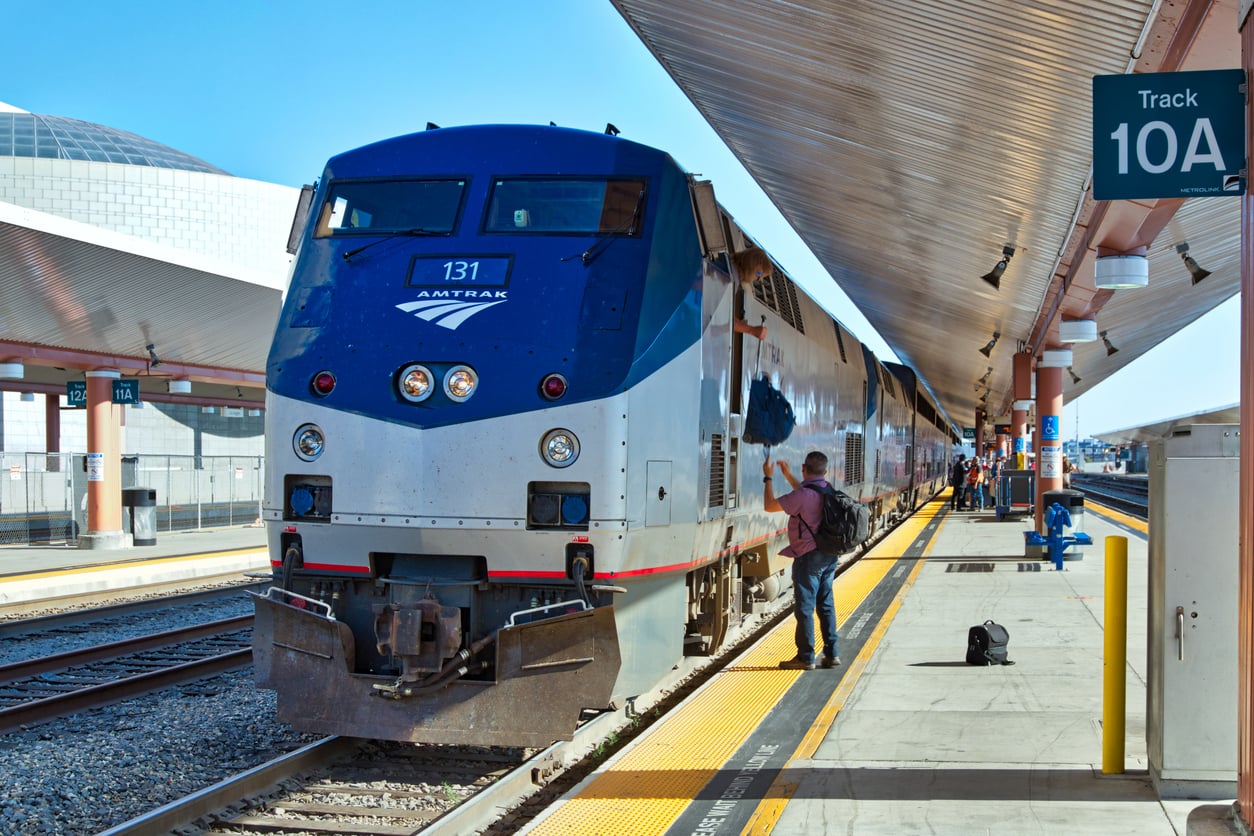
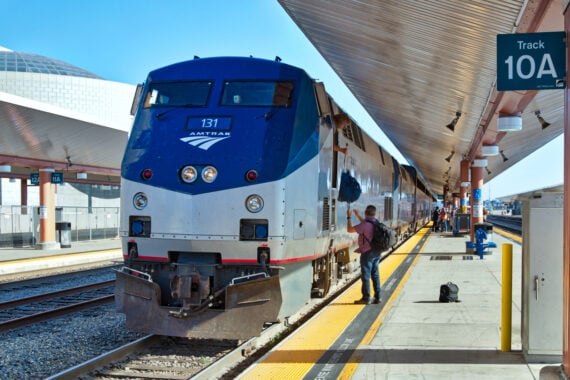
Retirees who automatically click the regular adult fare on Amtrak could be leaving money on the table. Travelers age 65 and older can receive 10% off most rail fares on most Amtrak trains. On qualifying cross-border Amtrak and VIA Rail Canada services, the senior discount starts at age 60.
There are exclusions, and promotional fares can occasionally be better, so “senior” shouldn’t become another price you accept without comparing. But if you’re eligible, it’s worth checking before buying a regular ticket — particularly if retirement gives you enough flexibility to compare routes and travel dates.
Retail Purchases on the Wrong Day
Waiting 24 hours to buy something isn’t usually considered a major financial strategy. For older shoppers, however, it occasionally pays surprisingly well.
AARP’s 2026 research found that retailers including Kohl’s and Ross Dress for Less offer older customers discounts on particular days. The rules can vary considerably, with different age requirements, exclusions, enrollment requirements, and restrictions on combining discounts.
So if a purchase isn’t urgent, check the store’s senior-discount policy before heading to the register. The exact same sweater, household item, or pair of shoes might be cheaper tomorrow simply because tomorrow is the right day to buy it.
Museum, Movie, and Attraction Tickets
It’s surprisingly easy to pay the standard adult admission price simply because that’s the option a ticketing website displays first. Before buying tickets to a museum, movie, zoo, historic site, theater, or other attraction, scroll a little farther.
Look for senior rates, matinee prices, weekday discounts, local-resident deals, free admission periods, and membership options. AARP’s 2026 money-saving guide specifically includes entertainment among the areas where consumers can find savings.
If you visit the same museum, zoo, or attraction regularly, do the math on an annual membership as well. What looks more expensive upfront may cost less than buying several individual tickets throughout the year.
Anything Before Asking About a Discount
Sometimes the money-saving strategy really is as simple as asking one question before pulling out your wallet.
Businesses don’t necessarily volunteer every available discount, particularly when a customer needs to show identification, join a loyalty program, verify a membership, or shop on a particular day. AARP’s 2026 retail research found that senior-discount requirements vary considerably and may include proof of age or enrollment.
So whether you’re booking a hotel, buying groceries, paying for entertainment, or making a retail purchase, get into the habit of asking whether there’s a senior, AARP, AAA, veteran, loyalty, or off-peak rate available. You won’t always get one, but asking takes considerably less effort than clipping a week’s worth of coupons.
Paying Full Price Shouldn’t Be Automatic
Saving money in retirement doesn’t have to mean structuring your life around coupons and clearance racks. Some of the biggest opportunities are benefits and discounts that already exist — you just have to know to look for them.
National park passes, grocery discount days, Medicare assistance, free tax preparation, health-plan fitness benefits, travel discounts, and senior retail days can all leave more money in your budget without requiring much sacrifice. A good rule of thumb is simple: Before paying full price for a recurring or substantial expense, spend two minutes checking whether your age, membership, insurance, income, or timing qualifies you for something better.